
Read this article in 中文 Français Deutsch Italiano Português Español
ERA/IRN RentalTracker: Q2 survey sees fall in confidence
21 July 2026
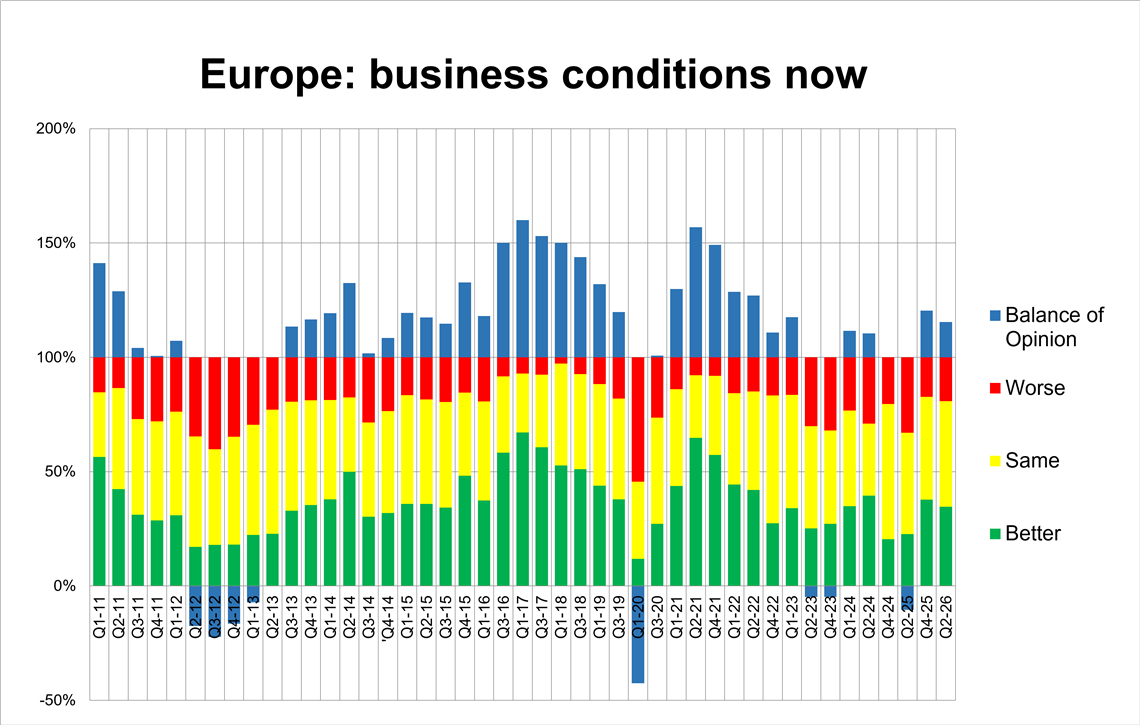
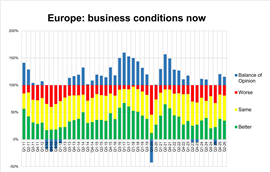 Business Conditions Now, end of Q2 2026
.
The Middle East conflict seems to have had a clear impact on confidence levels in Europe’s equipment rental industry. Murray Pollok reports on the ERA/IRN RentalTracker survey for the second quarter of 2026.
There have been few major changes in sentiment since the last RentalTracker survey undertaken at the end of 2025, with Europe still in a two-track environment. France and the UK are still reporting difficult business conditions, while Spain continues to lead the way in virtually every measure, from recruitment intentions to CapEx plans.
Overall, the improvements in business sentiment reported in January this year have been maintained, but not improved, and in some cases (notably the UK) sentiment has declined. Not surprising, perhaps, when you factor in the start of the US-Iran war.
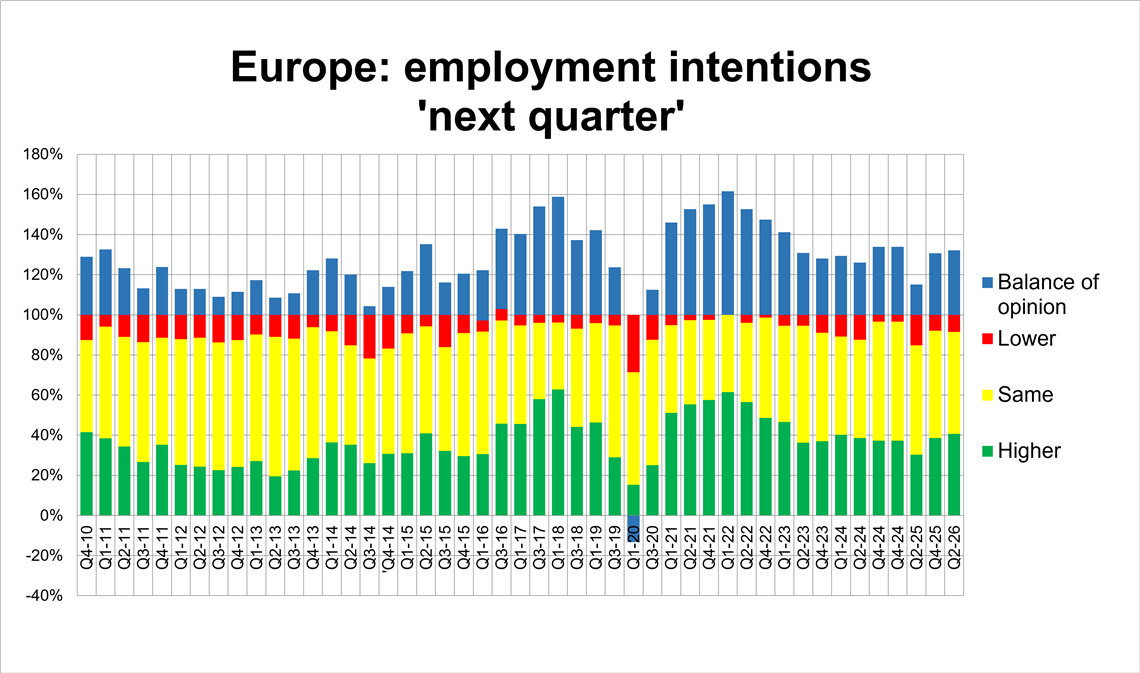
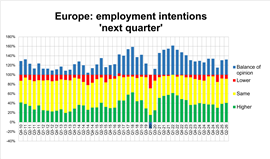 Employment intentions for Q3 2026.
There was a lower overall response to the survey – Europe’s holiday season has started – but with around 80 responses there is still plenty of data to consider.
Business conditions now
In terms of ‘business conditions now’, the positive balance of opinion fell slightly to +15%. It was +20% six months ago.
The quarter-on-quarter comparison of activity levels for Q2 2026 against Q2 2025 sees a similar picture, with a still positive balance of opinion of +15%, but down from +21% at the end of 2025.
In part this fall will be the result of a lower response from relatively more positive Italian companies and a holding up in responses from the UK and France, which are the two least positive countries of recent surveys. (The geographic make-up of the respondents can have a marked impact on the results.)
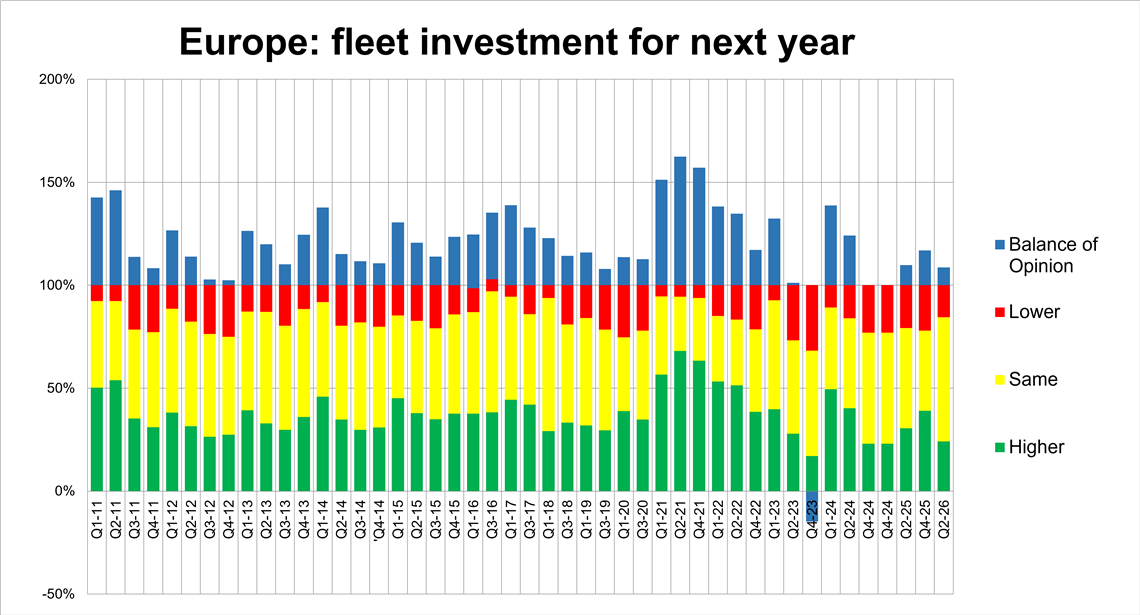
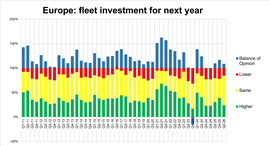 Forecast of CapEx in 2027.
The same applies with fleet capital investment plans for 2027. There is still a positive balance (+9%), meaning more companies will increase spending next year than reduce it, but that balance is lower than the +17% reported at the start of the year.
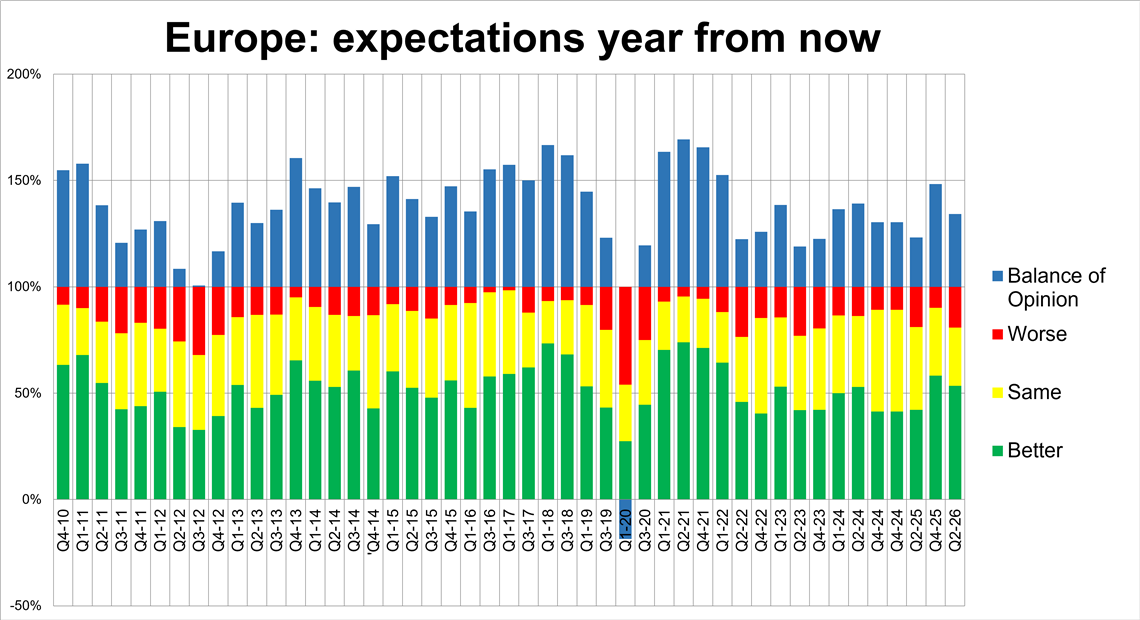
What about expectations for 12 months ahead? While the positive balance has reduced from six months ago, it is still healthy at +34% (it was +48% in January). In other words, 53% of respondents are expecting 2027 to be a better year while 19% expect it to be worse.
Reversal on utilisation
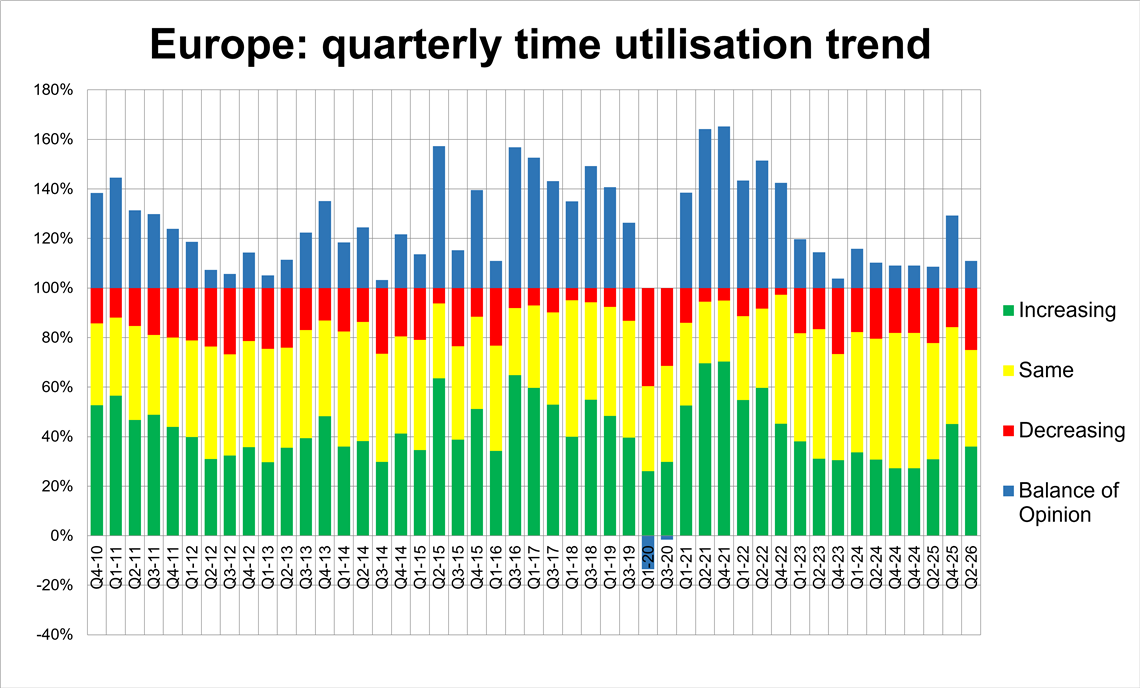
Time utilisation also sees a reversal on the positive finding of the previous Q4 2025 survey. There is a +11% positive balance of opinion against the +29% of the previous survey.
In employment intentions – we ask whether companies will recruit more staff in the third quarter of this year – there was an overwhelmingly positive response, with 41% wanting more staff and just 8.5% expecting to reduce their workforce.
As in previous surveys, this is likely to reflect the wider issues around recruitment and retaining staff that many rental companies in Europe face. That is a concern that is reflected in the decision by the European Rental Association to create a new People committee.
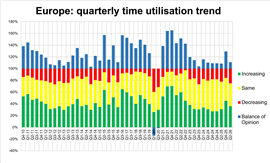 Utilisation rate trends, Q2 2026.
The lower response rate of this survey makes it difficult to say anything meaningful about the German and Italian rental business environments.
However, what is clear is that Spain remains the fastest growing major rental market in Europe. If some of the heat has come out of their survey numbers – 71% rather than 100% expecting an improvement ‘next year’ – that reflects the already high levels of confidence.
UK remains subdued
The UK remains in a subdued frame of mind, and it is notable that in every single measure – current conditions, utilisation, recruitment, Q2 activity year-on-year – the results show a deterioration since the start of the year. More positive is the finding that 31% of respondents from the UK and Ireland expect to increase their investment in fleet next year.
France also remains in a similar position. In fact, the key measures for France are almost identical to those of the UK, although without the relative positivity around investment: not a single respondent from France expected to increase CapEx next year.
In the last survey in January, we heralded a modest by significant recovery in confidence in Europe’s rental industry and anticipated a continuation of that. The Middle East conflict, and the resulting energy cost increases, seems to have generated a mild reversal.
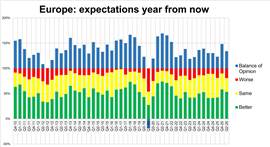 Expectations 12 months from now, as of end Q2 2026.
Note
The RentalTracker survey is carried out by KHL Group on behalf of the European Rental Association (ERA). We thank all the companies and rental associations in Europe who helped to distribute the survey. If you have any questions, contact: Murray Pollok, [email protected]
STAY CONNECTED
Receive the information you need when you need it through our world-leading magazines, newsletters and daily briefings.
CONNECT WITH THE TEAM